




 $HNRG
What happened
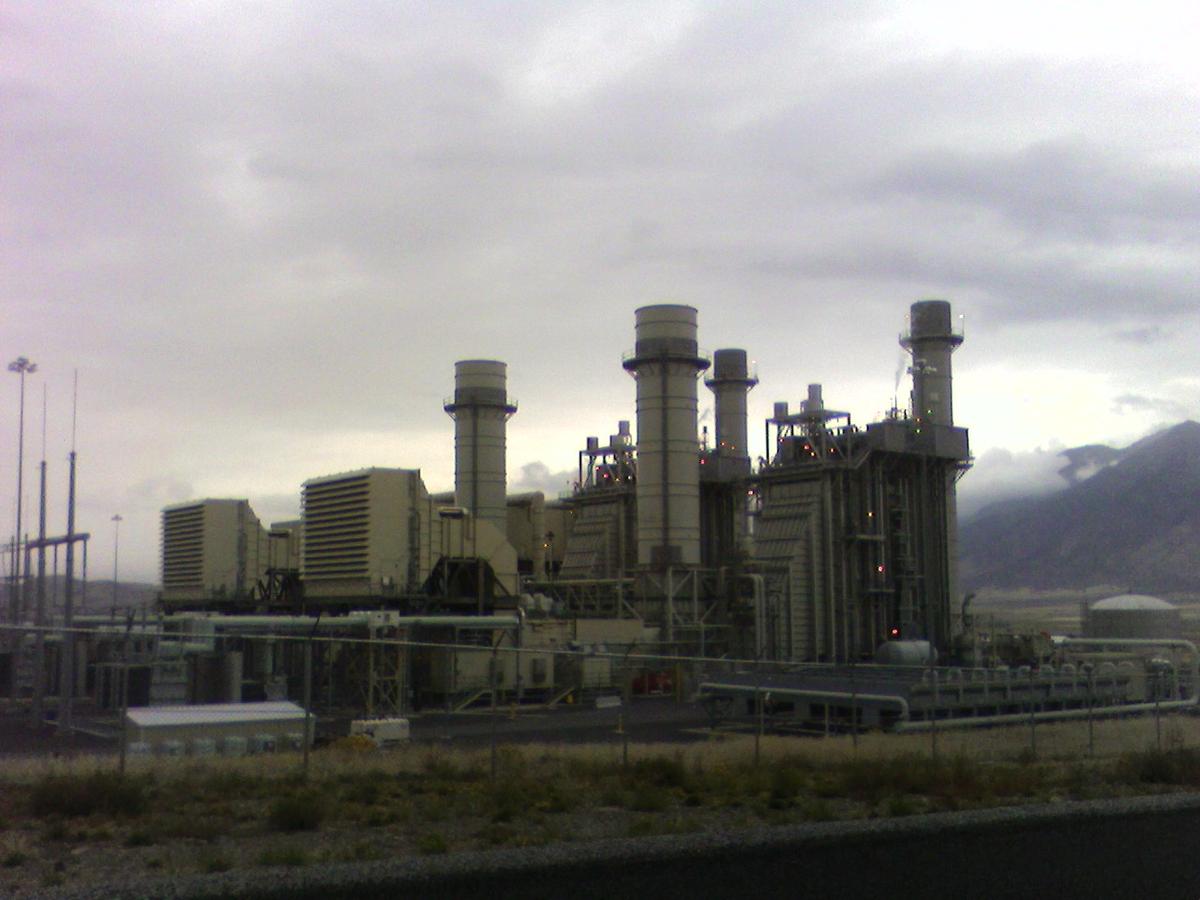
Hallador Energy Company (NASDAQ: HNRG) secured $600 million of debt for Turtle Creek, moving its proposed gas plant closer to construction.
It funded $550 million when the deal closed September 15. Another $50 million can be drawn during the next 12 months if the project stays on schedule. Hallador Energy Company (NASDAQ: HNRG) may also seek a separate revolver of up to $75 million, but that facility is not committed.
Before this filing, the central question was whether the company could finance a project expected to cost less than $800 million. At June 30, available liquidity was $84.2 million. Closing the term loan changes that assumption, even though it does not settle the full funding need.
Why it matters
The $550 million headline is not all available for construction. About $120 million will repay the company's existing term loan and revolver. Subtracting those repayments leaves roughly $430 million before fees and other uses. That is meaningful financing, but it is not the same as a fully funded $800 million project.
The money is also expensive. Before commercial operation, the loan charges 3.5% in cash, the secured overnight financing rate, and 4.5% as payment-in-kind interest. With the financing rate's 3.5% floor, the minimum economic rate is 11.5%. On $550 million outstanding, that would equal $63.25 million of annual interest, including at least $44 million added to principal rather than paid in cash.
After startup, the loan charges the financing rate plus 8% in cash, still at least 11.5% under the floor. The agreement also sweeps excess cash after commercial operation and secures substantially all company and project assets.
This reduces the risk that Turtle Creek stalls for lack of a lender. It replaces that risk with a demanding construction and debt-service test. The initial term is three years. A two-year extension needs lender approval and a 3% fee.
What's next
Watch whether Hallador Energy Company (NASDAQ: HNRG) qualifies for the $50 million delayed draw, obtains the proposed revolver, and keeps project spending within its estimate. Reported capital spending and payment-in-kind interest will show how quickly the financing cushion narrows.
The investment case is stronger on financing availability, not yet on project economics. It improves if Turtle Creek starts on schedule and contracted power sales support cash interest and principal payments. It weakens if construction slips, debt compounds faster than expected, or refinancing becomes necessary before stable cash generation.